Tax Plan 2027
17 september 2026
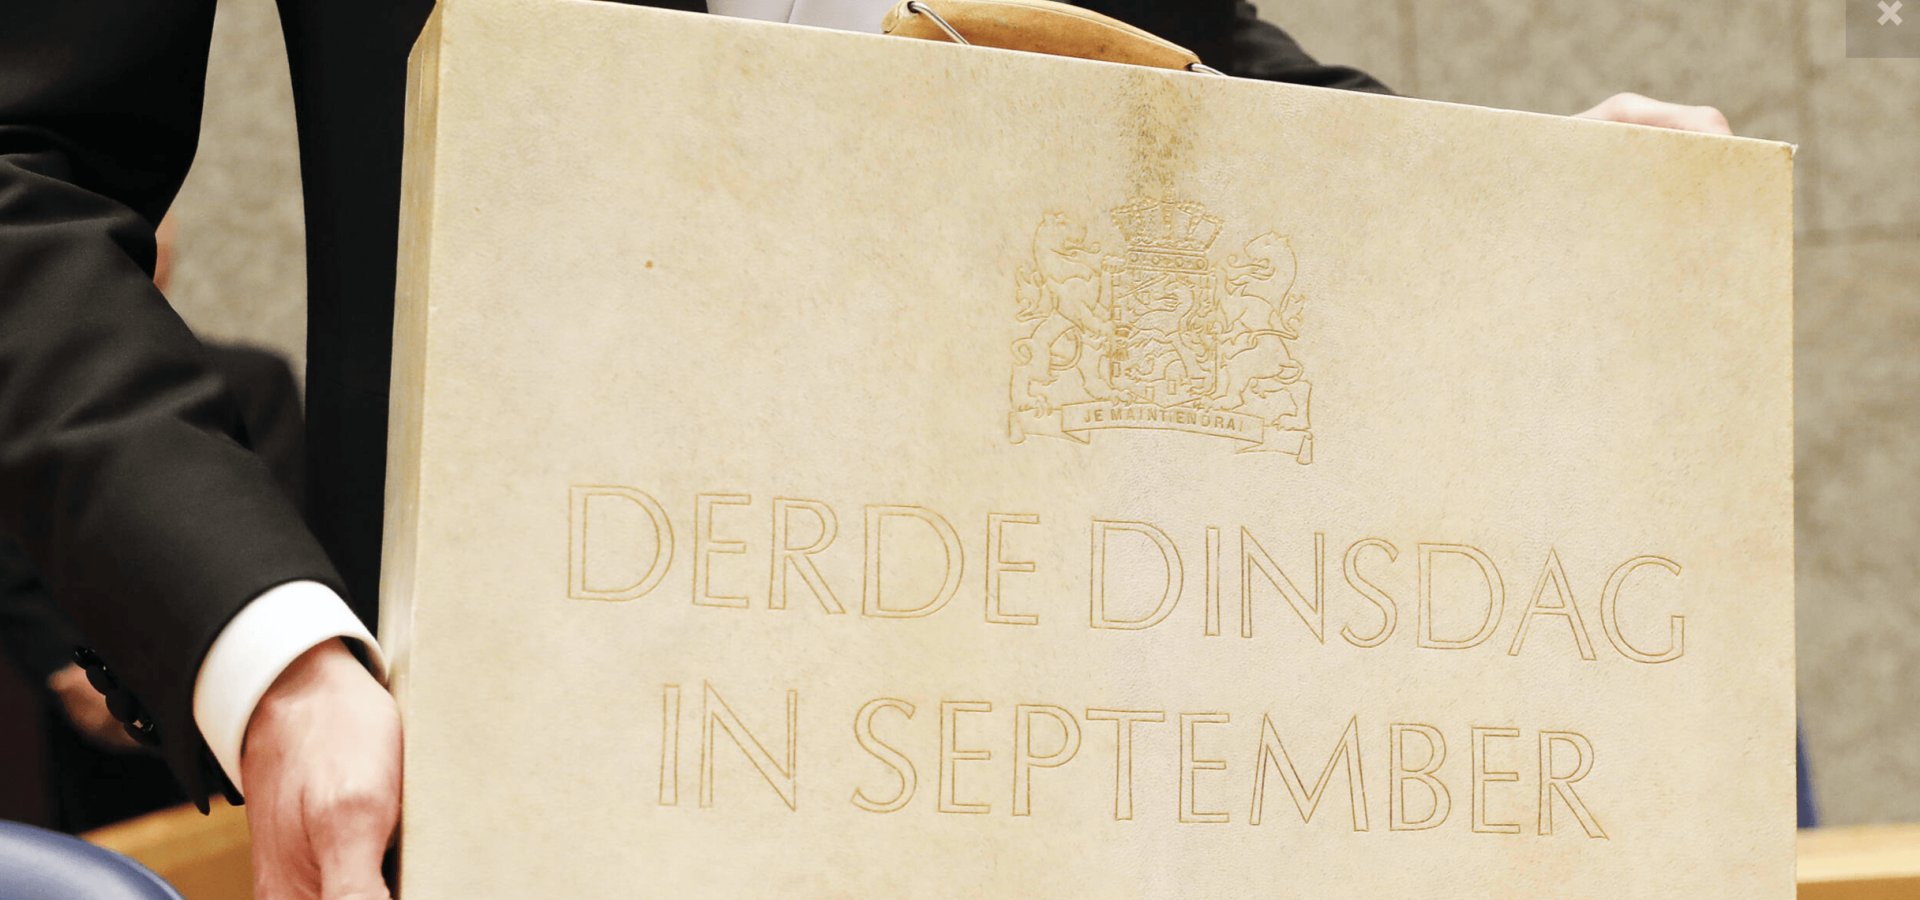
On Dutch Budget Day, the Dutch government submitted a series of legislative proposals to the House of Representatives. Please find below a summary relevant for business and other organization which work cross-border, including some proposals which were already announced earlier. Given that this is a minority coalition, significant changes during the parliamentary process remain likely, and the proposals should be regarded as a starting point for negotiations with the opposition:
- For Dutch corporate income tax purposes, the innovation box forfeit regime is expanded. The annual cap rises from €25,000 to €100,000 per taxpayer, making the regime more accessible for smaller businesses.
- The anti-abuse rules applicable to reorganisations (mergers and demergers) are amended following a Supreme Court (Hoge Raad) ruling which held that the second presumption of abuse, under which a disposal within three years of a merger or demerger was automatically deemed abusive, was incompatible with EU law. This second presumption is therefore removed. The first presumption (no business reasons where there is no restructuring or rationalisation) and the substantive abuse test remain unchanged.
- The exemption for hedging instruments used to cover currency risk in the context of the participation exemption is restricted. As of 2027, only the unexpected exchange rate movement (the deviation from the priced-in rate) remains exempt from 2027 onwards.
- Four new safe harbor rules for Pillar Two are introduced, largely in line with OECD agreements, reducing the compliance burden for qualifying groups.
- The Dutch real estate transfer tax rate for non-primary residences (rental properties, holiday homes) is reduced from 8% to 7%.
- The tax-free travel allowance for employees increased retroactively from €0.23 to €0.25 per kilometer as of 1 January 2026.
- The final levy of 12 per cent on fossil-fuelled passenger cars that are also used privately are being relaxed in a number of respects.
- Employees of qualifying start- and scale-ups benefit from a more favorable share option regime. Taxation is deferred to the moment of sale, and only 65% of the above-grant-date gain is included in wage.
- As regards personal income tax, no changes to the taxation of savings and investments in box 3 will be implemented for the time being. Various scenarios are still under discussion.
- An amendment is introduced to prevent unintended double taxation on inherited shares that consitute a substantial interest in combination with excessive with excessive borrowing from one's own BV.
- A refund scheme is introduced for Dutch natural persons and legal entities who are entitled to Dutch dividends through a foreign investment fund investing in the Netherlands.
- The starter's deduction (startersaftrek) for personal income tax purposes is reduced to virtually nil in 2027 and will possibly be abolished entirely in 2028.
- The revision of VAT on high-value services will come into effect on 1 January 2026. This applies to services with a fee of €30,000 or more (excluding VAT) and includes, amongst other things, renovations and alterations to immovable property.
- The reduced VAT rate for ornamental horticulture (e.g. flowers and plants) and balloon flights is abolished per 1 January 2028, after which the standard 21% rate will apply.
The above is a brief summary and does not constitute advice. We would be happy to assist with your specific situation.
Regarding tax advice or questions about this blog, please contact Peter van Dijk (vandijk@dayonelegal.nl)or Laurence Bos (bos@dayonelegal.nl)
Voor verdere informatie over deze blog of advisering over het onderwerp, kunt u contact opnemen met DayOne advocaat Peter van Dijk.
+31 6 46 15 61 86 | vandijk@dayonelegal.nl
+31 6 46 15 61 86 | vandijk@dayonelegal.nl